Thursday, 12 January 2012

IDENTIFYING SERVICE QUALITY DIMENSIONS BY UNDERSTANDING CONSUMER PREFERENCES IN THE MALAYSIAN GROCERY RETAIL SECTOR


IDENTIFYING SERVICE QUALITY DIMENSIONS BY
UNDERSTANDING CONSUMER PREFERENCES IN THE
MALAYSIAN GROCERY RETAIL SECTOR


Nor Khalidah Abu
Universiti Tun Abdul Razak
khalidaha@email unitar.edu.my


Rosmimah Mohd Roslin
Universiti Teknologi Mara
rosmimah@salam.uitm.edu.my


ABSTRACT
Increasing competition in the grocery retail sector in Malaysia has moved many retailers regardless of size, to find competitive edges that could place them ahead of the rest. The prominence of foreign based retailers that are predominantly large in size is worrying the small and medium sized retailers. Yet, their attraction toward different types of grocery retailers may differ as Malaysian consumers become more discerning in their choices of retailers. This study explores the needs of customers frequenting retail outlets of different sizes and evaluates the service quality dimensions which should be given priority by retailers wishing to establish firm competitive edge. Results reported are exploratory and based on interview results. Findings suggest the existence of all dimensions from findings of Retail Service Quality Scale (RSQS) by Dabholkar, Rentz, and Thorpe, 1996. However, specific issues related with physical aspects and personal interaction differs for different sizes of grocery stores. This study also highlight the existence of halal as a critical dimension for grocery shopping in Malaysia.

KEY WORDS: Malaysian retail, Service Quality, Grocery


INTRODUCTION
Grocery retailers in many developed nations operate in mature markets where growth opportunities are very slow and intense competition often shaped the way they operate. In Europe, the struggle for market shares has led many retailers to look for international options and very often international expansion is seen as the key to continued growth. It is therefore inevitable that the world market becomes the target for many established retail players as they look for new areas for expansion (World Retail Congress, 2008). Yet, differing consumer needs in international markets dictate that international retailers understand local preferences (Etger and Rachman-Moore, 2007). Rigby and Tricks (2005) observed that Tesco, for example, strives for a local feel to its international stores, but, in a concept known internationally as ‘Tesco in a box’, it also rolls out some of its successful UK practices, such as multi format stores, supply chain management and own label goods. In Malaysia, modern supermarkets and traditional outlets have always co-existed and the findings by Zain and Rejab (1989) have indicated that household income has been the factor that influenced consumers’ attractions to different types of outlets. Generally, in Malaysia, traditional retail stores and ‘wet markets’ have always attracted the low and middle income shoppers whilst modern retail formats are attractive to the upper middle income group and beyond. This, however, appears to be changing as improved consumer lifestyles and changing preferences are altering the way Malaysian consumers shop.

The Retail Sector in Malaysia


Malaysia, a Southeast Asian nation that is fast developing in tandem with the growth of the region, has often looked at foreign direct investment as the engine for further development. Private investment was growing strongly at 10.2% in 2004 and this reflected a positive growth that influenced other areas of the economy (Asia Economic Monitor, 2005). In line with the growth, the Malaysian government has always been keen to promote Foreign Direct Investment (FDI) where FDI inflows have become more broad-based with a higher share of new flows shifting towards higher value added activities in the services and the manufacturing sector (Bank Negara Malaysia, 2004).

The distributive trade sector is one area which has seen the migration of foreign investments. Grocery
retailing, especially, has been the target of many foreign firms and since 1992 with the emergence of Dutch based Makro into the distributive scene, the country now attracts other foreign names such as France’s Carrefour, the U.K’s Tesco, and Hong Kong based DFI which operates the Giant supermarkets and hypermarkets, Cold Storage supermarkets and Guardian Pharmacy chains. Table 1 indicates major supermarket and hypermarket in Malaysia.

Table 1

     Major Supermarket / Hypermarket in Malaysia
     Sources: Malaysian Business (2007) and * Price Waterhouse Coopers (2004)

Of late, retail sizes and the growing dominance of large scale retailers have been the contention of many local retail operators that are predominantly operating small, independent outlets. It is common for retailers to be differentiated on the basis of their retail sizes. Based on the definitions provided by the Malaysian Ministry of Domestic Trade and Consumer Affairs and integrating this with other theoretical definitions (Zainal Abidin, 1989; Ministry of Domestic Trade and Consumer Affairs, 2004), hypermarkets are defined as those with retail sizes in the range of 2,000 to 4,500 sq. meters while small provision shops are those operating stores less than 400 sq. meters The supermarkets are those with store sizes ranging between 400 to 2,000 sq. meters. The supermarkets are deemed closer to the hypermarkets in terms of their retail strategies although their merchandise assortment may be somewhat limited.

To a large extent, the foreign based competitors brought with them new retail concepts and attractions that are definitely attracting a large proportion of Malaysian consumers. Malaysian shopping preferences changed with the introduction of large scale retailing and their shopping habits are now dictated by more primary factors than merely merchandise attractions. This exploratory study is therefore a step at identifying retail dimensions that attract Malaysian consumers to shop at certain grocery outlets and its implications on strategic retail development. Using Dabholkar, Thorpe and Rentz’s (1996) service quality dimensions as a basis, this study ascertains Malaysian consumers’ views on what they perceived as important dimensions in influencing them to patronize particular grocery retail outlets.

Consumer Behaviour and the Malaysian Population

Malaysia is classified as an upper middle income country and is considered as one of the most developed of the developing nations (Price Waterhouse Coopers, 2004). The lifestyles of Malaysian have evolved and changed in line with the growing affluence and the increase in the education level of the population. High profile retailers and global mass media influence have played a role in shaping the lifestyles and buying preferences of Malaysians. Malaysians are becoming more sophisticated with westernized preferences in their buying behaviours. It is this kind of lifestyles that is propelling the growth of more modern retail formats and thus changing the distributive landscape of Malaysia. Small traditional provision stores that are mostly operated by local individuals are finding it increasingly difficult to survive in a market where changes in consumer lifestyles and preferences are dictating the type of retailers in the industry. The increasing dominance of the foreign owned hypermarkets are indeed changing the way Malaysians shop. 

Uusitalo (2001) finds that consumers look at store size as an important feature for store categorization. Similarly, in Malaysia, consumers patronize retail outlets that are differentiated on the basis of their sizes. Consequently, their shopping behaviour appears to be influenced by the different store formats where purchase size is often larger and they may be more receptive to store brands when frequenting large grocery outlets (Rosmimah and Sofiah, 2004). However, there is still a need to develop an understanding of consumption that is embedded in a grounded approach where an amalgamation of relevant dimensions can be included in assessing consumer preferences (Clarke, 2000).

Service Quality in Grocery Retail Environment

Due to intangibility nature of services, it is difficult to measure service quality as there are fewer tangible cues available when consumers purchase services (Parasuraman, Zeithaml, and Berry, 1985) as compared to goods. Service also requires higher consumer involvement in the consumption process (Grönroos, 1984) which makes it more complicated to measure. 

Several researchers operationalize the service quality construct either as a gap between expectation of service and perceived performance of service, or just perceived performance alone (Hurley and Estalami, 1998). Other researchers see service quality dimensions as the criteria to assess service quality (Parasuraman, Zeithaml, and Berry, 1985; Feinburg, de Ruyter, Trappey and Lee ,1995). The later claimed that service quality dimensions are instruments for measuring perceived service quality and it is seen as a multi-dimensional construct. 

In a competitive environment, service quality is critical for service firms to maintain a stronghold position (Parasuraman, et al., 1985, Shemwell et al., 1998; Mehta et al., 2000) as it is an indicator of business performance (Hurley and Estelami, 1998). Based on superior service, smaller stores could compete with larger and more powerful stores (Klemz and Boshoff, 1999) as they could not compete on price. In addition, focusing on service quality is important in markets where product offerings are similar (Berry, 1986), as typically found across grocery retail stores.

Improvement of the quality of services requires identification of the service quality dimensions that are important to retail customers. Although the research into the dimensions used by consumers to measure service quality in the service sector is extensive, there is lack of empirical studies on factors of quality improvement strategies (Odekerken-Schröder et al., 2001), especially the service quality dimensions (Dabholkar et al., 1996) for the retail sector. SERVQUAL by Parasuraman et al., (1985), the most famous and well discussed service quality model in the 1990s (Robinson, 1999) failed to befully adopted and validated in a retail setting (Dabholkar et al.). Service quality measurement of the retail stores, unlike the pure service setups, should include the measure of service quality and product quality as retail stores offer a mix of services and products (Mehta et al., 2000; Dabholkar et al., 1996).

Dabholkar et al. (1996) developed the Retail Service Quality Scale (RSQS), a multilevel structure with three different levels: an overall perception of service level, a dimension level, and a subdimension level. The multilevel idea was triggered by other findings that claim the existence of high correlations among SERVQUAL items across factors and the evaluations form by customers at different levels (Dabholkar et al.). As a result, the researchers claimed that customers evaluate retail service quality at a dimension level, a subdimension level, and at an overall level. The researchers adopt 17 items from SERVQUAL and added 11 items based on their research. The five dimensions are named physical aspects, reliability, personal interaction, problem solving, and policy.

Although RSQS has high construct reliability and validity (Dabholkar et al, 1996), a need to look into quality dimensions for each country is called for. Each country is believed to have its own unique set of quality dimensions (Xiande Zhao et al., 2002) with different levels of importance (Feinburg et al., 1995). Consumers’ attitudes towards food shopping are associated with culture (Samsinar et al., 2001) and therefore, any findings from previous studies in other countries may be irrelevant in Malaysia. Currently there is lack of research on service quality of retail stores in Malaysia specifically consumers’ service quality perceptions of the different sizes of stores. Several researches have concentrated on service quality of businesses namely courier companies (Norbani Che Ha and Sharmila Sinnathurai, 1999), automotive industry (Tan, 1998), and financial institution (Ndubisi, 2003) and service quality of government department (Sharifuddin Zainuddin, 1997). There is also a gap in the literature on the measure of service quality among competing retailers (Dabholkar et al.) in particular of different sizes.

This study explores the changing needs of Malaysian consumers in selecting grocery retail outlets in an environment where the retail environment is now predominantly dominated by foreign large scale retailers. The needs of Malaysian consumers as they select grocery retail stores are very much influenced by factors that are not necessary tied to only demographic characteristics. Income level need not necessarily be the only factor influencing retail choices. Malaysian consumers are now more discerning and may select retail stores in accordance to specific preferences.

RESEARCH OBJECTIVES

The study aims to:
First, explore the needs of customers frequenting retail outlets of different sizes.
Second, evaluate the service quality dimensions which should be given priority by retailers wishing
to establish firm competitive edge.


RESEARCH METHODOLOGY

A qualitative study was employed as an initial step towards gathering factors that were likely to point to service quality characteristics. A qualitative method is deemed appropriate at the exploratory level as it provides an openness that is typical of qualitative inquiry. This allows the researcher to focus in-depth on a subject while at the same time understand the complexity of social interaction and uncover the underlying implications of such complexity. The adoption of qualitative approach in social studies enhances the chance of uncovering the complex nature of social interaction between individuals at different levels of the social system. According to Glesne and Peshkin (1992), this approach avoids simplifying social phenomena and instead opens the door towards exploring and understanding the range of human behaviour in the process of interaction.

In line with Dabholkar, Thorpe and Rentz’s (1996) Retail Service Quality Scales (RSQS) in assessing service quality of retail stores, this study tries to identify dimensions that could indicate consumer’s preferences in frequenting certain type of grocery stores that are peculiar to Malaysians. RSQS include the measure of service quality and product quality suitable for retail store (Mehta et al., 2000; Dabholkar et al., 1996) and the scale is found to be valid in Malaysian setting in relations to the apparel specialty store (Yeap, T. Ramayah, Jasman J. Maaruf, 2004)

The mall intercept method was utilized where seventeen customers visiting selected grocery retail outlets in Klang Valley, an urban area (Jamaliah, 2004) were intercepted while shopping and interviewed to gauge the reasons for shopping in particular outlets. Nine retail outlets were divided on the basis of their different sizes, i.e. three small stores, three medium sized outlets or supermarkets, and three large scale retail outlets or hypermarkets. Open ended questions were posed to gauge the reasons customers patronize these outlets and why they would not patronize other outlets. Responses generated were then analyzed qualitatively through content analysis and rigorous exercise of categorization. Through the process of open, axial and selective coding procedures, themes were generated and categorizations were formulated to provide clarity in assessing the qualitative responses (Strauss and Corbin, 1990). Connections between categories were developed and validation of dimensions identified was justified through references to statements made by respondents. The findings were further strengthened by relating them to existing literature pertaining to retail preferences (Zain and Rejab, 1989; Sofiah, 2001).

FINDINGS

The process of transcribing and analyzing responses reveal several factors pertinent to customers’ patronization of stores. Qualitative analysis requires an extensive evaluation of the transcripts and this is further grounded with existing literature. Service quality dimensions identified by Dabholkar et al. (1996) are cross checked with the findings and there appears to be similarities as well as new dimensions that are relevant to the Malaysian environment.

The findings indicate overlapping of responses for customers frequenting outlets of different sizes. All dimensions relating to service quality of retail outlets as identified by Dabholkar et al. (1996) are present for all types of grocery stores from the interviews. However, what are peculiar in this study as compared to the researchers are the specific issues surrounding physical aspects and personal interaction which differ for different size of stores.

For physical aspects the following demonstrate the difference across different store sizes. 

For small stores, location is considered important as the following response suggest: “It’s simply easy to go, parking is near (to store) and the store is small.”

For the hypermarkets, convenience is associated with internal environment: 
“What we want is all in one place.”

“At G it is easier because it is on a single floor. That is why it is easier to shop in G.”

“ ...if we want to eat, we go to T. Besides buying groceries, we can buy food at the food court.”

This is typical of Malaysian consumers who look at grocery shopping as a family outing where itinerary
almost always include eating and window shopping as the following comments suggest:

“J is better…in terms of its ambience. Its cleaner, it’s nicer to see. Sometimes we go shopping not to buy grocery but to enjoy. Take a walk…”

Personal interaction between customers and retail staffs is also a factor of interest. In the small stores and the medium sized supermarkets, individual attention is often commanded whilst for the large hypermarket, personal interaction relates to the cashiers at the check-out counters as the following comment suggests:

“If we want to pay, there is no long queue. Fast…just pay.”

Although, customers do not expect personal attention be given, large hypermarkets should still have retail assistants who are well trained and willing to assist those in need. This may not always be the case as related in the following response:

“My mum is very old and there is this one time when she asked…where is the sugar? and the guy just said, Oh, that side and that’s it and we have to go and find it ourselves. They are not that helpful…..They are not friendly. They don’t know how to appreciate customers. So, I took a long time after that to go there again.”

Regardless of size, there is still a need for some personal interaction between retailers and customers in any retail settings. Personal interaction is perhaps a dimension that is not easy for large retailers to provide but its importance has been pointed out and this may well become a competitive edge for the large stores that already possesses many other differentiating characteristics.

Another dimension which is unique to Malaysia is the dimension related to halal. “Halal” is an Arabic word for “permissible” which applies to food products, meat products, food ingredients, and food contact materials in a grocery store. Although 60% of the Malaysian population are Muslims (Melati Mohd Ariff, 2004), many grocery stores are foreign owned or operated by non-Muslim Malaysians. Operators’ ignorance on the sensitivity of Muslims in Malaysia may affect the grocery store choice as
demonstrated below:

“So we feel not confidence. Hesitant. This chicken ..halal or not halal. I’m afraid. That’s why I don’t go
there.”

“I don’t go to C because I think they also put stuffs like the non-halal (counter). And whenever I pass those .. whenever I want to go to the grocery part, I pass that place and maybe it’s not smelly but to me my sensitive nose. I think I smell something. I didn’t like it. So, I don’t go to C.”

“Like chicken or fish. I am not confident. Because the freezer I worry they mix with the non-halal.” 

The halal dimension was first suggested to measure customer service quality (SQ) in Islamic banking (Othman & Owen, 2001) and later insurance institutions (Izah Mohd Tahir & Wan Zulqarnain Wan Ismail, 2004).

PROPOSITIONS

Based on the analysis, the following propositions are developed:

First, consumers expect some service quality dimensions to be present in all grocery retail outlets, regardless of store size.
Second, physical aspects of the store are important dimensions that attract customers to patronize grocery retail outlets.
Third, personal interaction is deemed important as an influencing factor for customers to patronize a grocery retail outlet.
Finally, halal dimension is a new dimension identified to influence grocery shoppers to patronize a grocery retail outlet.
These propositions need to be evaluated further to assess the extent of their applicability in influencing store patronage. As such, a quantitative study may be essential in the next study in proving the propositions statistically.

CONCLUSION

This exploratory study has established that Malaysian consumers may share similarities in terms of relevant dimensions pertaining to service quality when frequenting retail stores, yet, the underlying reasons may differ for stores of different sizes. This is the key to establishing competitive edges as small stores compete with large retailers in attracting customers. Grocery shopping for Malaysian consumers is not merely a routine exercise but a family experience where food and window shopping is part of the itinerary. Therefore, the trip to a supermarket or a hypermarket is looked upon as an outing that involves more than just buying groceries. Although small retailers or provision stores are becoming functional where they are frequented merely for purchases of small, low value items, their competitive edge however, lies with the personal attention given to each customer and the invidualized services that could be developed for customers considered a priority to the store.

The hypermarkets have the resources to offer a large array of customer services but those considered vital should be the ones they concentrate on. This includes offering attractive complementary stores around the hypermarkets as well as fine eateries that cater to the needs of Malaysians of different ethnic backgrounds. Appearance is an essential dimension and store ambience and atmospherics play important roles in attracting customers. Indeed, these are dimensions that have already been given much attention but at times neglected because of differing priorities. Like other consumers in the Southeast Asian region, Malaysians have peculiar needs which multinational retailers that are keen to expand into this country may need to consider as competition increased from local retailers as well as other international competitors looking for international expansion.

REFERENCES

Bank Negara Malaysia (2004, August 3). Remaking Malaysia: investing in the new Malaysia, Governor's opening address at the Euromoney Conference. Kuala Lumpur. Retrieved on August 2, 2008 from http://www. bnm.gov.my.

Berry, L. L. (1986). Retail businesses are services businesses. Journal of Retailing, 62(1), Spring, 3-6.

Clarke, I. (2000). Retail power, competition and local consumer choice in the UK grocery sector. European Journal of Marketing, 34(8), 975-1002.

Dabholkar, P., Thorpe, D. I., & Rentz, J. O. (1996). A measure of service quality for retail stores: scale development and validation. Journal of the Academy of Marketing Science, 24(1), 3-6.

Etger, M., & Rachman-Moore, D. (2007), Determinant factors of failures of international retailers in foreign markets. The International Review of Retail, Distribution and Consumer Research, 17(1),
79 -100.

Feinburg, R. A., de Ruyter, K., Trappey, C., & Lee, T.Z (1995). Consumer-defined service quality in international retailing. Total Quality Management, 6 (1), 61-67.

Glesne, C., & Peshkin, A. (1992). Becoming qualitative researchers: An introduction. White Plains, New York: Longman.

Grönroos, C. (1984). A service quality model and its marketing implications. Journal of the Academy of Marketing Science, 24(1), Winter, 36 – 44.

Hurley, R. F., & Estelami, H. (1998). Alternative indexes for monitoring customer perceptions of service quality: A comparative evaluation in a retail context. Journal of the Academy of Marketing Science, 26(3), 209 – 221.

Izah Mohd Tahir & Wan Zulqarnain Wan Ismail (2004). Customer service quality in insurance industry: The case of Islamic insurance. International Borneo Business Conference, Kota Kinabalu, Sabah, Malaysia. December 9-11.

Jamaliah Jaafar (2004). Emerging trends of urbanisation in Malaysia, Journal of Department of Statistics Malaysia, 1, 43-54.

Klemz, B., & Boshoff C. (2001). Environmental and emotional influences on willingness-to-buy in small and large retailers. European Journal of Marketing, 35 (1/2), 70-91.

Mehta, S. C., Lalwani, A.K., & Soon Li Han (2000). Service quality in retailing: relative efficiency of alternative measurement scales for different product-service environments. International Journal of Retail & Distribution Management, 28(2), 62-72.

Melati Mohd Ariff. (2004). Malaysia: A hub in the making for Halal Food? Retrieved September 2005 from http://www.miti.gov.my/halalhub-new16feb04.html.

Ministry of Domestic Trade and Consumer Affairs (2004). Foreign guidelines on foreign participation in trade and distributive trade services.

Ndubisi, N. O. (2003). Service marketing: are perceptions of service quality predictors of behavioral intentions? The Malaysian Borneo banking industry perspective. Proceedings of the Academy of Marketing Studies, 8(1), 37-44.

Norbani Che Ha & Sharmila Sinnathurai.(1999). Dimensions of service quality by courier companies: Consumers’ perception. Malaysian Journal of Consumer and Family Economics, 2, 129-141.

Odekerken-Schröder, G., De Wulf, K., Kasper, H., Kleijnen, M., Hoekstra, J. & Commandeur, H. (2001). The impact of quality on store loyalty: A contingency approach. Total Quality Management, 12(3), 307-322.

Othman, A. & Owen L. (2001), Developing an Instrument to measure customer service quality (SQ) in Islamic banking. International Journal of Islamic Financial Services, 3(1), 1-26.

Parasuraman, A., Zeithaml, V. A., & Berry, L.L. (1985). A conceptual model of service quality and its implications for future research. Journal of Marketing, 49, Fall, 41-50.

Pointing, J., & Teinaz, Y. (2004). Halal meat and food crime in the UK. Paper presented at the International Halal Food Seminar, Islamic University College of Malaysia, Kuala Lumpur, Malaysia.

Price Waterhouse & Coopers (2004). Malaysia: Global retail and consumer study 2004/2005

Rigby, Elizabeth & Tricks, Henry (2005, June 13). Tesco needs to look beyond home front. Gulf News.

Robinson, S., (1999). Measuring service quality: current thinking and future requirements. Marketing Intelligence and Planning, 17(1), 21-32.

Rosmimah Mohd Roslin & Sofiah Abd Rahman (2004). Impact study of hypermarkets on small traders. Ministry of Domestic Trade and Consumer Affairs. Unpublished report.

Samsinar Md Sidin, Yong Onn Soon, A., & Lim Siak Kwan. (2001). The relationship between employment status, perceived time shortage, and food shopping concerns: A study on the Malaysian wife. Malaysian Journal of Consumer and Family Economics, 4, 49-58.

Sharifuddin Zainuddin (1997) An analysis of perceived service quality in the road transport Department of Malaysia, Unpublished PhD Thesis, University of Pittsburgh.

Shemwell, D.J., Yavas, U., & Bilgin, Z. (1998). Customer-service provider relationships: An empirical test of model of service quality, satisfaction, and relationship oriented outcome. International Journal of Service Industry Management, 9, 155-168.

Slowdown Filters to Street Level Asia Economic Monitor (2005, April 30)

Sofiah Abd. Rahman (2001). Consumer awareness and acceptance towards retail brands: A case for Malaysian Department Stores. Paper presented at the Sixth National Seminar on Malaysian Consumer and Family Economic Conference, Kuala Lumpur, Malaysia.

Strauss, A., & Corbin, J. (1990). Basics of qualitative research: Grounded theory procedures and techniques. Newbury Park, CA: Sage Publications.

Tan Thiam Keat (1997). Customer service quality as a competitive strategy in the Malaysian automotive industry. Unpublished MBA thesis. Universiti of Malaya.

Uusitalo, Outi (2001). Consumer perceptions of grocery retail formats and brands, International Journal of Retail and Distribution Management, 29(5), 214-225.

World Retail Congress (2008), Changing global economic order points to key brand expansion opportunities. Retrieved August 2, 2008, from www.worldretailcongress.com.

Xiande Zhao, Changhong Bai, & Y.V. Hui, (2002). An empirical assessment and application of SERVQUAL in a mainland Chinese department store. Total Quality Management, 13(2), 241- 254.

Yeap Ai Leen, J., T. Ramayah & Jasman J. Maaruf (2004). Validating a retail service quality instrument in apparel specialty stores. Paper presented at the International Borneo Business Conference, Kota Kinabalu, Malaysia, 3-5 December 2004.

Osman Zain & Ismail Rejab (1989). The choice of retail outlets among urban Malaysian shoppers. International Journal of Retailing, 4 (2), 35-45.

Zainal Abidin Md. Said (1989). Retailing in Peninsular Malaysia.Arena Buku: Kuala Lumpur.

Thursday, 10 November 2011

A Simple Model of Personal Branding


In business and entrepreneurship, we often talk about “business model” and “revenue model”. Put simply, a business model describes how a business work and compete.  A revenue model says how the business earns its revenue and profit.
It’s my first time to come up with a more formal model on real life problems. It is not meant to be complete or entirely accurate.  A model is just a representation of the real world.  It is meant to help us make decision on real life problems. It has weaknesses and we shall not depend on a model entirely.
I came up with this model on personal branding as I’m preparing for a talk on the topic.  The model doesn’t try to cover everything about personal branding. Nor does it explain why we should do brand our self, or how to go about doing it. But it’s more on the elements of personal branding and the kind of questions we should ask our self when developing and evaluating our own personal brand.
Ricky's model on personal branding
I hope to elaborate more on the model soon. But for now, I’ll let the mind map do the talking. Click on the map to get the full picture. If you can roughly get the ideas I want to convey simply by looking at the mind map, then I know my mind mapping skill has improved :)
Your comments and criticisms are much welcome.

Tuesday, 8 November 2011

Mattel 2006 Annual Report


Mattel 2006 Annual Report -

Saturday, 29 October 2011

Entrepreneurship in Society_3/23/2011 - Keith Baisden

Entrepreneurship in Society_3/23/2011 - Keith Baisden


Entrepreneurship in Society_4/15/2010 - Steve Hannah and Mike McAvoy

Making a Name for Retail

April 1, 2008

Thanks to local and national partnerships, UW-Madison’s Center for Retailing Excellence is flourishing once again.
About three years ago, a group of UW-Madison alumni debating the revival of the School of Human Ecology’s Center for Retailing Excellence asked many retail companies what their opinions were on the school’s graduates. The overwhelming answer: “We don’t know.”
One executive, though, the CEO of Kohl’s Department Stores, said he would get back to them.

Kelly Mansell, a UW-Madison retail major, helps put out merchandise as part of her student internship at The Purple Goose, a Verona clothing store, arranged with help from the UW’s Center for Retailing Excellence.
“He did a little research, and called back and said, ‘Well, we hire more from UW, they stay longer and they promote faster. We like it a lot. What can we do to help it be better?’” says Jerry O’Brien, the center’s director. Using a seed grant of $200,000 from that company, along with other prominent sponsors such as Target and Shopko, O’Brien was hired to reinvigorate the center, which had become less active over time due to funding issues.
Besides making a name for UW-Madison students among retail companies, another main objective for the center is promoting retail as a career path for all types of students — from history to retail to pharmacy majors — and dispelling myths about working in retail. Myths such as low pay and long hours are untrue, O’Brien says.
“Our goal with the students is to introduce them to the wide variety of careers that the industry offers. Most students are aware that you can be a buyer or a store manager, but there's so much more to it than that,” he says.

Networking, internships benefit students

While many companies contribute financially to the center, which operates without state funding, they also are involved personally with students through networking or career-related events, a lecture series, a symposium class that features a weekly speaker and by hiring interns. Students can intern nationally at major corporations such as Macy’s, which is headquartered in New York, regionally at companies such as Kohl’s and Land’s End, and locally at stores such as The Purple Goose, a Verona-based women and children’s clothing store.
The owner of The Purple Goose, Halley Jones, says she began hiring UW-Madison student interns as soon as she opened her store in October 2005 — even before the Center for Retailing Excellence had been revived.
“I just love interns,” she says. “They just bring this energy because they’re here to learn. Things change all the time in retail, and they're really excited about different ideas that we come up with together and trying different things.”

Jerry O’Brien
When O’Brien first contacted Jones to become involved in the center, she took him up on his offer, agreeing to speak at one of the symposium’s class meetings. She says she enjoys being involved because she can offer a unique perspective as a smaller, more localized retailer to students, both those in class and those serving as interns.
Students seeking jobs and internships also benefit from the center’s close relationship with upper-level management at many larger companies. Amy Katschnig, a UW retail major and president of the Retail Club, says she was having trouble looking for an internship in the fall of 2006. She would apply online, but often would not hear from companies or get past an initial interview. During a trip to Chicago organized by the center, she met contacts for the American Girl Company and Crate and Barrel, and was eventually offered internships at each. Beyond the trip, she adds, the events orchestrated by the center and the Retail Club help students ease into networking with retail employers.
“We all know … that networking is so important, but it’s really intimidating to go to someone in this company because you think they have all the power in the world, and you’re just a student here who doesn’t know that much,” she says. “So I think that the small events and just keep encouraging students to network — it breaks down some of that intimidation factor, so that really helps.”

Working toward responsible growth

While getting funding and helping students and companies connect has been the center’s initial focus, School of Human Ecology Dean Robin Douthitt says the next step is focusing on research. One of the biggest advantages of UW-Madison that the alumni task force noted is its strong graduate schools and research tradition, she says. Developing research projects with specific companies can create a mutually beneficial relationship by improving a retailer’s business while allowing graduate students to work with real data and issues in retail.
O’Brien adds that a grant from the Kauffman Foundation is also allowing the center to discuss creating a separate symposium for privately owned, smaller retailers to discuss starting their own businesses. Another project involves linking together alumni to form a contact database among retailers.
“It’s very exciting. The truth of the matter is, the hardest thing is prioritizing where we should go next,” he says. “We want to do what we do well, then go on.”

Standing up for business

September 15, 2009

Madison, WI – When Zoe Moore, innovation Network Manager for Vestas Global Research, was challenged with the task of forming a partnership with the University of Wisconsin-Madison, where did she turn for help?

When David Ryder and his company, MillerCoors, wanted to donate fermentation equipment to the university, who did he trust to broker the initial contact?
And when UW-Madison MBA student Farhan Ahmad needed help getting his new business off the ground who did he ask?

The answer to all of these questions is the UW-Madison Office of Corporate Relations (OCR) and its campus collaborators. To find out how OCR helped these individuals, and could help you and your business, read OCR’s 2008-09 Annual Report, now availablehttp://www.ocr.wisc.edu/about/ocr_reports/ 

Now in its sixth year, OCR continues to foster relationships between business and industry and UW-Madison. This year’s Annual Report highlights two of OCR’s more recent university-corporate partnerships. 

Contact: Doug Bradley                        
(608) 263-0238
bradley@ocr.wisc.edu 

Time is Money

February 1, 2005

How the Center for Quick Response Manufacturing's time-based solutions slash manufacturing costs, lead times.
By Bill Shepard

In the fall of 2002, Chuck Gates, president of RenewAire Inc., was facing some tough choices as orders were increasing for the company's residential and commercial lines.
"We had grown by 37 percent that year, and we weren't sure how we were going to take the next step," says Gates.
Photo: Chuck Gates, president of RenewAire Inc., speaking with Rajan Suri, director of the University of Wisconsin-Madison's Center for Quick Response Manufacturing.
Chuck Gates (right), president of RenewAire Inc., in the company's Madison facility with Rajan Suri, director of the University of Wisconsin-Madison's Center for Quick Response Manufacturing. 
Gates' Madison-based company, which manufactures energy-recovery ventilation systems that solve indoor air quality problems while simultaneously saving energy, had received increased orders for both its residential and commercial lines. But this welcome "problem" of growth also presented some tough choices.
One option was to expand the plant, purchase more equipment and hire more staff to meet future growth. But there wasn't time for that, and besides, this would have been costly and potentially risky. After all, if RenewAire's growth spurt ended up being short-lived, pursuing a major plant and staff expansion would have been a grave error.
Another option was to continue operating at current capacity, yet avoid taking on new business — in essence, saying "no" to further growth. But for most companies, actually turning down business is simply unthinkable.

There was a good alternative
Fortunately for Gates, he found an alternative that allowed him to say "yes" to more growth by increasing capacity while using his existing staff and manufacturing facilities.
How did he do it?
With help from the faculty and students of the University of Wisconsin-Madison's Center for Quick Response Manufacturing, RenewAire's operations were revolutionized by the principles of quick response manufacturing.
"We dramatically increased our production capacity, yet we did it all within the same footprint, without having to expand our facilities or make additional investments," Gates notes.
Since 1993, the Center for Quick Response Manufacturing (QRM) has provided a forum for learning about the concepts of quick response manufacturing, enabling companies to bridge the gap from the theoretical to the practical, from the classroom to the enterprise.
"In a sense, factories and businesses are our 'laboratories' for testing and proving the theories of QRM," says Frank Rath, QRM associate director.

Changing the face of manufacturing
Through student team projects involving the analysis of businesses' real-life challenges and problems, as well as seminars, conferences, case studies and publications, the Center for QRM is dramatically changing the face of manufacturing at large and small companies around the world.
Just what is quick response manufacturing?
"There are many continuous improvement systems out there that focus on reducing waste and non-value-added overhead, but this system is unique in that it focuses on relentlessly reducing lead times in all aspects of a company's operations. This in turn results in the elimination of waste, improved quality and reduced costs," explains Rajan Suri, director of the QRM Center and author of the book "Quick Response Manufacturing: A Companywide Approach to Reducing Lead Times."
Speed and the ability to adapt quickly are the keys to competitiveness in today's marketplace. For companies that have production volumes that vary or possess a high degree of customization, quick response manufacturing can be just the ticket.
Central to the theory and practice of quick response manufacturing is manufacturing critical-path time, or MCT, which is the typical amount of calendar time from when an order is created, through the critical path of designing, engineering, fabricating, assembling, packing and shipping, until the first product is delivered to the customer.

The key to cutting waste
The longer the MCT, the greater the amount of waste. But the key to cutting waste is to measure each step of the manufacturing critical-path time to determine when people are actually working on the product and when it is laying idle, awaiting the next phase of production.
In the case of RenewAire, students from the Center for QRM carried out time-based studies of the company's operations to pinpoint different types of idle time.
"The students conducted 'job tagging,' in which they attached tagging sheets to individual jobs, in order to determine the manufacturing lead times and individual processing times associated with each operation," Gates said. "For example, we found the average manufacturing lead time for high-volume units was over two days."
The QRM student teams also conducted "multi-observational studies" of what RenewAire workers were doing at any given time to identify non-value-added activities, such as walking around looking for tools or parts or waiting for tools or parts to be delivered.
As each of these non-value-added activities mount, lower productivity results and lead times get stretched out. In turn, longer lead times cause companies to stockpile larger inventories, adding warehousing costs to the mix. Longer lead times also result in increases of cancellations or order changes or obsolescence due to warranty changes. All of these scenarios can be costly to companies.
But by eliminating idle periods in manufacturing critical-path times, companies such as RenewAire in turn can remove waste and unnecessary costs and can bring products to market more quickly.

Spotting room for improvement
When RenewAire received the results of the student teams' studies, it found that much wasteful idle time resulted from technicians walking around gathering parts and tools or looking for them. The biggest room for improvement was in RenewAire's commercial business. To remedy the problem, RenewAire decentralized its production flow into production cells, in which technicians have parts and tools right at their fingertips, so they don't have to walk back and forth to get them. By organizing tools and materials into a more efficient production configuration, idle time spent retrieving them from different plant areas was eliminated.
However, these improvements were just the tip of the iceberg. RenewAire has implemented more sophisticated QRM techniques, such as better planning methods for their workload, as well as POLCA (Paired-cell Overlapping Loops of Cards with Authorization), a method to manage capacity and space on the shop floor. As Gates points out, the results have dramatically improved RenewAire's operations.
"The university students' studies and recommendations, and the overall conceptual structure of QRM that we learned from the center — these were the tools we needed to build a more efficient, flexible business," Gates reflects. "The Center for QRM gave us a focus, a starting point to improve upon."

QRM has partners worldwide
Indeed, the UW Center for QRM has given focus to its many industry partners around the world, including the Trek Bicycle Corp. in Waterloo; Varco B.J B.V. in Etten-Leur, The Netherlands; and Irving Shipbuilding in St. John, New Brunswick, Canada.
One of the center's largest industry partners, the John Deere Worldwide Commercial and Consumer Equipment Division, has embraced the concepts of QRM, and even has built QRM concepts into its supplier relationships. The results of this enterprise-wide effort have been astounding. Manufacturing critical-path times were reduced by 94 percent for wiring, by 93 percent for hydraulic valves and by 87 percent for consumer garden tractor blades.
"The center provided training for John Deere's engineers, who in turn passed on the knowledge and concepts to the suppliers," Rath explains. "It began at the John Deere plant in Horicon, Wis., and has been implemented throughout the entire Commercial and Consumer Equipment Division headquartered in Raleigh, N.C."
Paul Ericksen, division manager of supply management services at John Deere Worldwide, was the key leader of Deere's supplier development initiative that focused on QRM and is perhaps one of QRM's most eloquent and persuasive proponents. He notes that John Deere's Commercial and Consumer Equipment Division has gained tremendous manufacturing flexibility from QRM.
"If you can flex up your production above what was forecast, that's almost like gold," Ericksen says. "And that's what our division is known for. When forecasts come in, if we need to flex up, we can boost 20 percent with two weeks notice. And if we need to change the model mix, flexing up in one model and flexing down in another — if something is selling and something else isn't — we can do that, too."

An edge over low-wage countries
While the UW-Madison Center for QRM is having a quantifiable, positive impact on companies large and small throughout the United States, Suri contends that it could give American manufacturers an edge over low-wage countries that have been absorbing manufacturing jobs in recent years.
"With this QRM approach, companies have reduced lead times by more than 80 percent and product costs by 20-40 percent," Suri states. "These reductions eliminate the labor cost advantage of overseas competitors, showing that local manufacturers can recover their competitive edge and retain significant numbers of jobs in this country."

Where CFOs Come From

March 1, 2005

The Applied Corporate Finance Program in the School of Business at UW-Madison takes on some weighty financial questions from industry, here and abroad.
When a major corporation needs some special assistance in financial management — such as suggestions on how to deal with the fact it that it may have too much cash on hand — it can turn to the University of Wisconsin-Madison's Applied Corporate Finance Program (ACFIN) for expert advice.
ACFIN is the specialized MBA program in the School of Business for students aiming for careers in corporate finance.

Professor Jim Seward teaching his MBA students.

Photos by Bob Rashid
Students in this small, intense MBA program are gaining a reputation for their competence, maturity and foresight as they work with organizations to come up with recommendations and solutions to companies' financial challenges. Each semester, teams of three ACFIN MBA students work on four separate projects.
Organizations such as John Deere, Deutsche Securities, Medtronic, Qualcomm, 3M, Procter & Gamble, Berbee Information Networks, Promega and American Family Insurance have used ACFIN student teams to help analyze various financial issues and challenges.

Training tomorrow's CFOs
While industry gains from their labor, the projects primarily are intended to provide growth and learning opportunities for the students, who often are the CFOs of the future.
They learn fast, according to Professor Jim Seward, who started the program in 1999. He says he sees them grow in confidence, competence and professionalism in each successive project.
"Sometimes, on their first project, students come to me and ask where they can find the answers, what references they should use," says Seward, who outlines team projects on one-page summary sheets. "I tell them to use everything they've learned until now and figure out what other resources they need. There is no right answer to these complex problems."
ACFIN teams are expected to distill everything they learned into a written presentation, then deliver their results in an oral presentation to CEOs and other high-level corporate executives. This experience gives students the opportunity to develop comfort with their own expertise as they face powerful executives, Seward says. He sees marked growth in competence as students move from their first project to their fourth.
"I almost think we should video tape before and after — to show the students' growth in confidence from their first presentation to their fourth," he says.

What can happen to a bad idea
Although Seward is available "100 percent of the time" for students as they work their way through complex problems, he says he will not speak at the actual presentations to the industry clients.
"I tell the students don't even look at me," he says.
He notes that if there is a mistake, or bad data, it could be torn to shreds by members of the sponsoring organization.
"I tell the students you don't know who's going to be in that room. If you're criticizing what you believe is a terrible idea, and the author of that idea and his boss are in the room, you're going to be in for a rough time," Seward says.
Students get research assistance from undergraduate finance students who serve as a part of each team. Advice also is available from ACFIN's 24-member board of advisers, executives in strategic finance positions around the country. Students often call on board members, says Seward, to help decide if they have covered all their bases as they work on their reports. Board members from organizations such as AOL Time Warner, Citigroup, UBS Securities can give them a broader perspective on issues.
ACFIN has worked with companies as small as four people, up to corporate giants such as Procter & Gamble and 3M.

What to do with $5 billion?
In most cases, the sponsoring businesses accept the students' oral and written reports and implement some — or all — of their ideas. In some cases, the advice is not taken. After doing a critical and strategic evaluation of the company with too much cash, the ACFIN team recommended the corporation give back between $4 billion and $5 billion to shareholders. The organization chose to give shareholders closer to $1 billion, but not because the answer was wrong.
"It was just too dramatic a move for the conservative company," Seward says. It was one of many real-world lessons students got as part of their ACFIN experiences.
ACFIN projects are performed at no charge to the sponsoring organization and present a wide variety of complex challenges. They range from evaluating characteristics of a company's major competitors to providing recommendations for improving internal financial reports. Students working with Kraft Foods, for example, were asked to determine the attractiveness — from a valuation standpoint — of acquiring more properties in the natural foods segment and to suggest strategies for growing that business segment.

Working in the international arena
Students recently took on a project that involved issues of hedging and risk management for Titan Petrochemicals & Polymers Berhad in Malaysia. Although many projects require an international perspective, it was ACFIN's first internationally based project.
Seward, who is the program's executive director, comes to Wisconsin from Dartmouth, where he taught a variety of finance subjects. ACFIN, he says, is the synthesis of everything he felt should be included in a program aimed at producing corporate finance officers. No other school has the level of student involvement in actual finance projects, he states. When he came to Wisconsin, he brought along many Wall Street contacts with him, and the desire to create a premier program in the area of corporate finance.
That fit right into the school's strategy of creating top-quality MBA programs that are career-focused. When Dean Michael Knetter came to the school in 2002, he deleted many of the school's MBA offerings. ACFIN not only survived, but a $6.4 million gift from Milwaukee financier Albert "Ab" Nicholas, with another $2 million from an anonymous donor, assured the program a future as one of the school's premier MBA programs. The home of the ACFIN program now is officially the Nicholas Center for Applied Corporate Finance. A grand opening of its new quarters was celebrated on Sept. 30.

How industry clients are served
ACFIN students enjoy the amenities of a top MBA program. While Seward works with students on the academic side, center Director Cindie Horner works to develop relationships with industry that include placement, internships and projects. She also coordinates ACFIN's alumni relations and board events and supervises the students who serve as research assistants to the ACFIN teams.
"Our ACFIN program is unique in the depth and breadth it offers students," says Knetter. "Jim Seward and Cindie Horner, with help from the gift from Ab Nicholas, have developed an outstanding applied corporate finance program — not only for Wisconsin, but as a model for anyone who wants to give their students real-world experience."

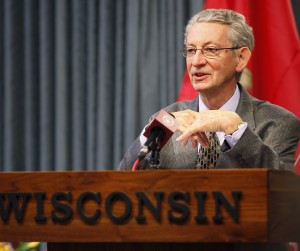
Q&A with David Ward: Interim chancellor sets agenda to reform UW finances Read more: http://host.madison.com/wsj/news/local/education/university/article_f1c97734-efb2-11e0-b47e-001cc4c03286.html#ixzz1cBgphbqt


David Ward may only be an interim chancellor, but he doesn't want the next two years to be wasted time for UW-Madison.
He's set out an ambitious agenda to implement newly gained authority from state government and reform the university's finances.
 "It's not a happy message," Ward said in an interview in his Bascom Hall office Wednesday, the day after his interim term was extended a year through summer 2013. "Even though people may applaud, a lot of them are very troubled by it. I don't see this as a quick fix."
Ward, 73, is a familiar face on Bascom Hill. He was chancellor from 1993 to 2001. Since Biddy Martin left in July and Ward took over, he's proved to be popular. It was in large part because of requests from students, faculty and staff members that his tenure was extended.
Here are edited excerpts of the interview:
Q: How did you make your decision to continue on for a second year?
A: I thought it would be a huge challenge to reassimilate. But to be very frank, it's like wearing old clothes. While the issues are different, functionally and culturally, the place seems to work like I remember it. ... Second thing, in terms of the extension, I tried to create a dialogue about change. Almost every public flagship institution is probably facing a revenue crisis. There's just not enough money to be of the quality we currently aspire to be. How can we use — if you like — self-help, as well as new money, to work our way through that? I want to create a dialogue about that.
Q: How did your wife (Judith Ward) feel about extending your term?
A: Whatever happens, I think we find it to be an adventure. It's not like committing the rest of your life. It's an incredible opportunity to do a limited number of things in a short period of time.
Q: Would you consider a permanent job as chancellor?
A: I wouldn't be an applicant. I'm old. I'll be 75 after two more years. My inclination is the university should look for younger leadership. I think I can be very helpful transitionally.
Q: You've said you've heard from almost everyone that salaries are a huge problem. Do you have a plan for bringing back raises or a pay plan?
A: I do think the morale-salary relationship is a problem. Having said that, I think everybody has to recognize that outside the university, it's not seen as a problem. In a recession, looking at a relatively high-paid, upper-middle-class occupation, if you're in a rural community or if you're in Racine, or even perhaps the East Side of Madison, there's something odd about this. I think there's an enormous communication problem in trying to express that issue. And by the way, the same is true of tuition increases.
Q: You've said the university needs to look to "self-help" to handle budget problems. What does that mean?
A: If we can find money in administrative savings, in rethinking how we're academically organized, or even persuade donors to think about the core budget as well as the excellence budget, maybe we can create a war chest that allows us to do something on the inside.
Q: Does that mean cutting jobs?
A: What it means is you resize. I'm not sure everybody gets cuts. There may be some areas where you have to increase as well. I'm not sure it's one-size-fits-all. ... Reallocation is something that universities have never — not just here, anywhere — been very good at.
Q: When will UW-Madison employees see pay raises next?
A: I don't know. What I'm suggesting would be very selective. I think it would have to be, maybe almost everybody receives it, but it would have to be based on merit. I think the challenge here is to do this in a way that doesn't arouse public ire.
Q: How would you gauge the university's relationship with the state Legislature?
A: I've met with leadership on both sides. I really wanted to see how they felt after the spring. It's fairly clear the idea of autonomy or independence for Madison is just not there politically. It's incumbent on me to figure out how I can help the (UW) System-campus relationship work more effectively. I think I've worked on that a lot. I've been very impressed by how Kevin Reilly and the (UW) Board (of Regents) have responded to the feeling of unhappiness with the System that came out of the debate about whether Madison should be a public authority.
Q: Are you a football fan? Predictions for Badgers season?
A: I came here in 1960, so I remember the Rose Bowl in '63, which I listened to on the radio. The next Rose Bowl was when I was chancellor. The next three. We won them, too. I'm a sports fan. I like ice hockey, too. ... It's very exciting to come back and see a very competitive team and see the kind of public bonding that comes from a football program. It's really a great form of outreach that we have.


Read more: http://host.madison.com/wsj/news/local/education/university/article_f1c97734-efb2-11e0-b47e-001cc4c03286.html#ixzz1cBgVMzD8